UK banks face 10,092 complaints over crypto transfer restrictions
 Phuong-Linh Nguyen
UK customers filed 10,092 complaints about difficulties sending money to cryptocurrency platforms during a 90-day period between May and August 2026, according to an October report by Stand with Crypto UK. The complaints came from 9,803 individuals, meaning some people submitted more than one.
The figures cover customers across all 650 UK parliamentary constituencies. They do not show how many transfers banks blocked or how many customers were affected beyond those who complained, but they record problems ranging from transaction limits to providers refusing crypto-related payments altogether.
Lloyds group had the most complaints
Lloyds Banking Group received 2,297 complaints, the highest total in the report. That figure includes complaints involving Halifax and Bank of Scotland customers. Barclays followed with 1,569, while NatWest Group, including Royal Bank of Scotland, received 1,278. HSBC UK was the fourth bank to record more than 1,000 complaints over the period.
The report also named Monzo, Santander UK, Nationwide, Revolut, Starling Bank, TSB and Chase UK. Virgin Money and Co-operative Bank had the lowest totals among the providers listed, with 103 and 76 complaints respectively. The figures count complaints, not necessarily distinct blocked transactions.
Limits differ between providers
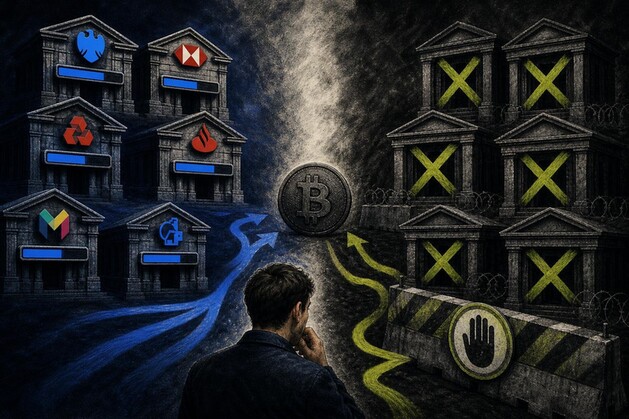
Some banks permit crypto-platform payments but cap how much customers can send. Barclays and HSBC UK each allow transfers of up to £2,500 per transaction, subject to a £10,000 maximum over 30 days. NatWest sets a daily limit of £1,000 and a 30-day limit of £5,000.
Santander UK caps an individual transfer at £1,000 and sets a monthly limit of £3,000. Monzo permits crypto-related transfers totalling up to £5,000 over 30 days, while Nationwide sets a daily limit of £1,000. Those differences mean the amount a customer can transfer depends on their provider and the relevant time period, rather than a single limit applying across the UK banking sector.
Other providers listed in the report take a stricter approach. Starling Bank, TSB, Chase UK, Metro Bank, Virgin Money and Co-operative Bank were identified as imposing outright bans on crypto-related transfers. Lloyds and Revolut had not officially announced restrictions, although customers of both reported problems completing payments. The distinction matters: a reported difficulty does not, by itself, establish that a bank has a formally published ban.
Campaign group calls for clearer decisions
Stand with Crypto UK wants banks to replace blanket bans and fixed payment caps with controls that take account of the customer and the individual transaction. It has also called for banks to explain clearly when they may block or restrict a crypto-related transfer, and why they have done so.
The group has asked providers to give customers a proper route to challenge a decision or seek an exemption when sending money to an FCA-registered or authorised platform. The report’s figures describe complaints about access to transfers; they do not indicate that every customer who contacted a bank was refused an appeal or exemption.
FCA framework will not require banks to process payments
The complaints come as the Financial Conduct Authority prepares a new crypto regulatory framework. The FCA opened its authorisation process on 30 September 2026. Firms have until 28 February 2027 to apply if they want to qualify for transitional arrangements.
That process does not oblige retail banks to handle payments to cryptocurrency exchanges. The framework’s introduction therefore will not, on the information in the report, remove the ability of individual banks to set their own transfer policies. Customers may still encounter provider-specific caps or bans.
For customers planning a transfer, the practical differences are material: the stated limits range from £1,000 a day at NatWest and Nationwide to £10,000 over 30 days at Barclays and HSBC UK, while six listed providers were reported to ban the payments outright. Stand with Crypto UK advises customers to keep records of blocked transactions and ask their bank to clarify its policy before attempting a payment.